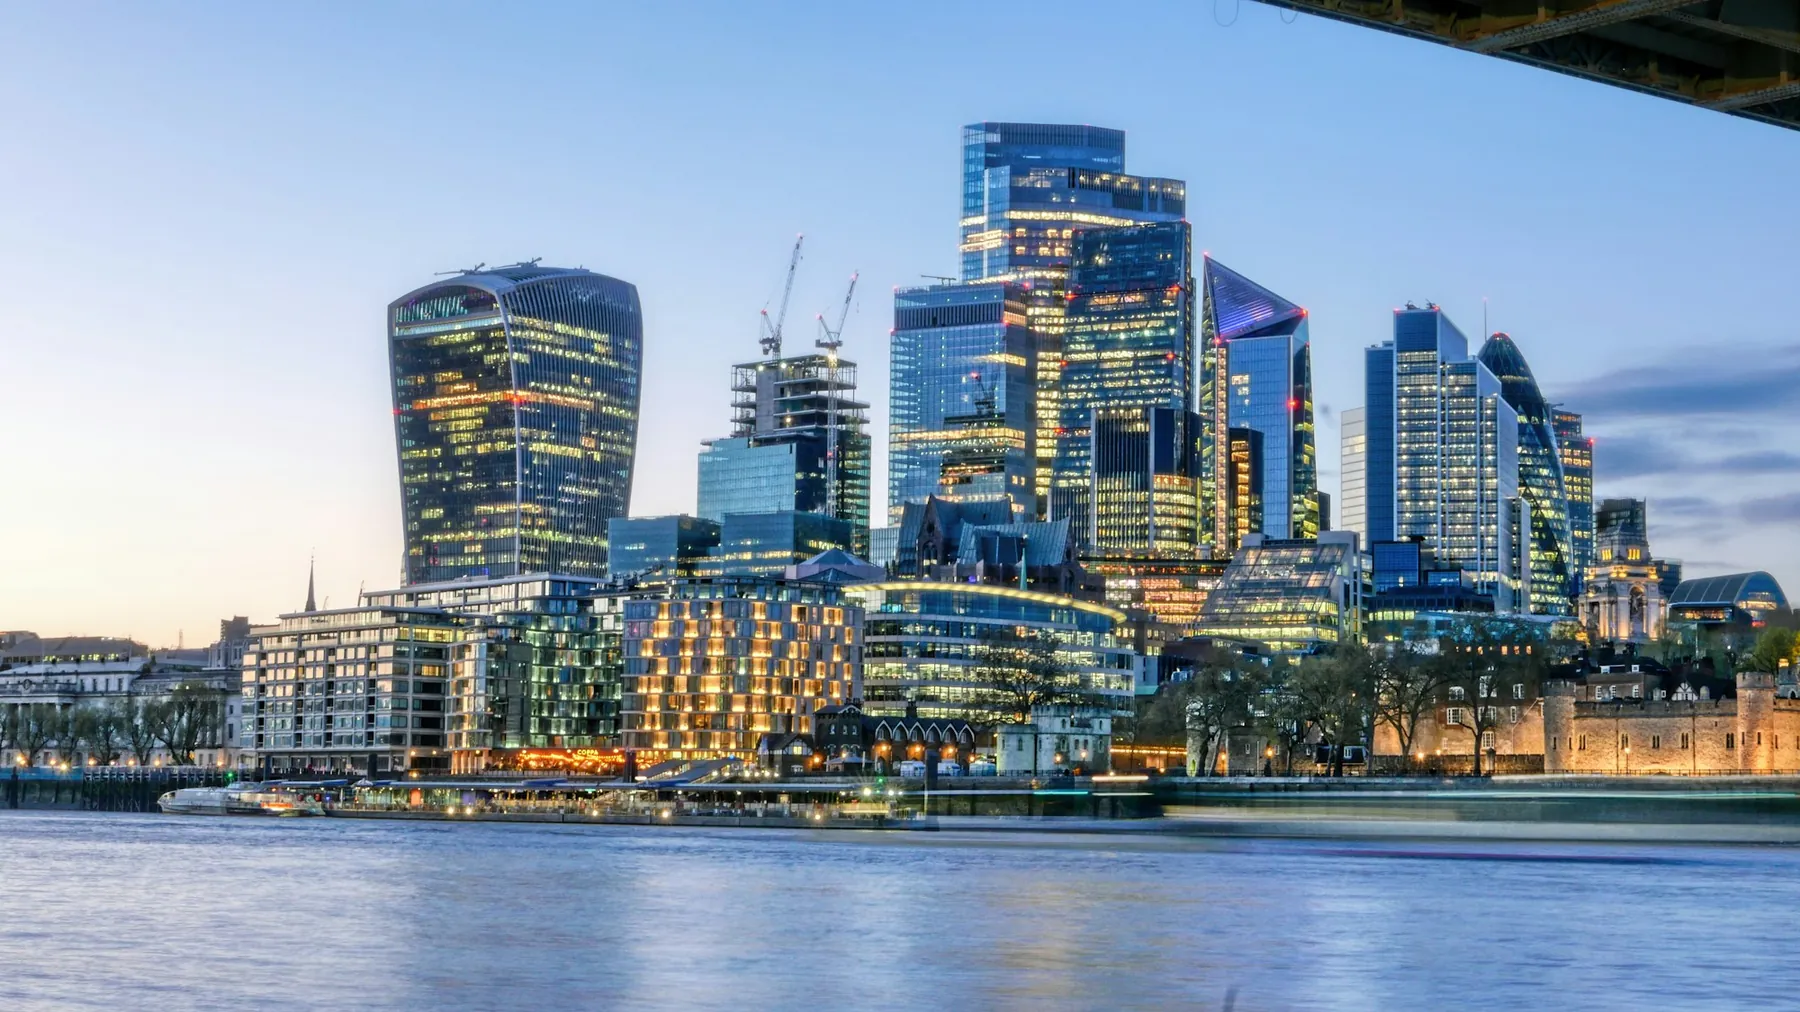
The world’s #2 financial centre, the UK’s deepest and most liquid property market, and a safe haven for global capital.
London generates over £569bn a year — around a quarter of the entire UK economy — and ranks as the world’s second financial centre, a single point behind New York. For investors it’s a capital-growth, liquidity and safe-haven play, underpinned by chronic undersupply.
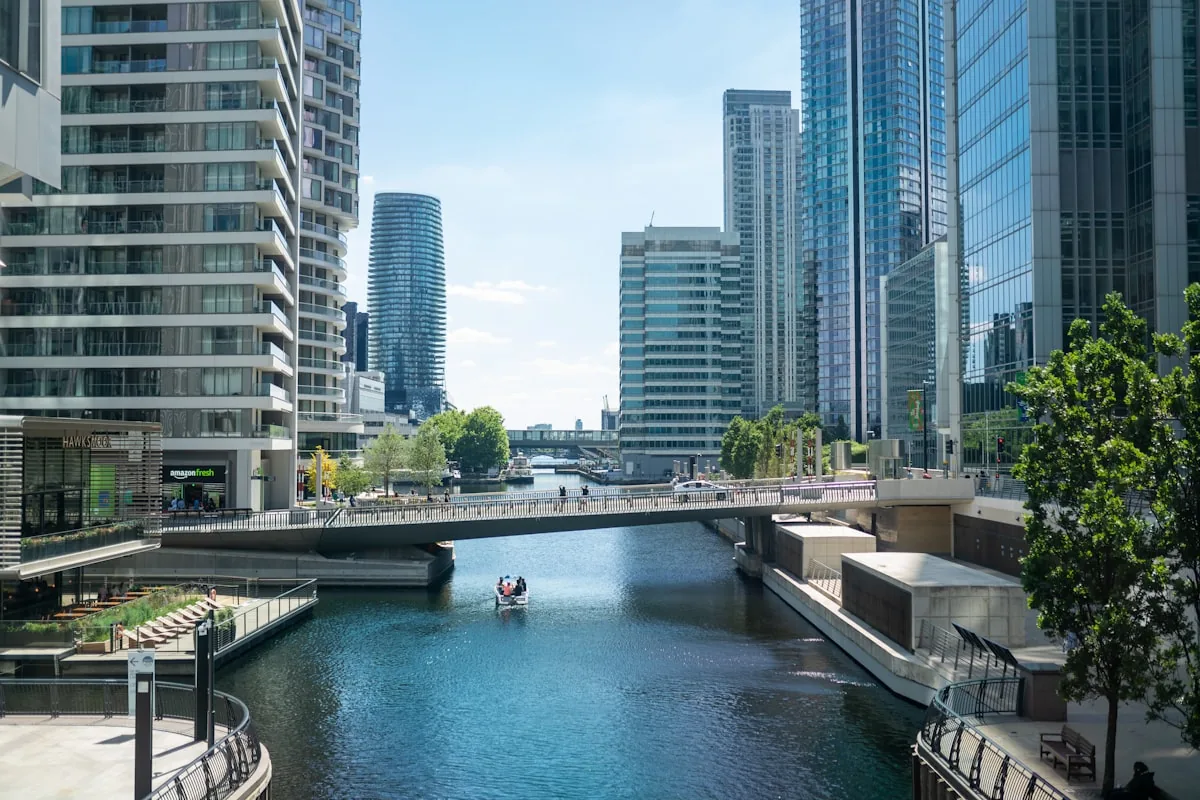
Canary Wharf financial districtLondon runs more active urban regeneration than any city in Europe — these are the schemes reshaping whole districts.
An HS2 super-hub and the UK’s largest rail interchange — 26,500 homes, 36,500 jobs.
Under constructionA new riverside district unlocked by the Northern Line Extension; the Power Station reborn.
Building outA 53-acre new town centre — 3,000 homes and 2m sq ft of workspace (British Land).
On siteOlympic legacy — now a culture-and-education quarter (UCL East, BBC, V&A).
DeliveringEurope’s newest major railway — 243m journeys a year, reshaping area values.
OpenDiversifying from pure finance into life sciences, residential and retail.
EvolvingAfter a soft 2025, JLL projects around 21.6% price growth for London over five years — with the structural housing shortage the core long-term driver.
Inner London runs on young professionals and a fast-growing build-to-rent sector; outer, new-build areas like Barking Riverside draw a mix of professionals and families on lower entry prices.
Six genuinely central neighbourhoods across Zone 1 — from HS2/Elizabeth Line regeneration to prime, capital-preservation streets.
The US Embassy relocation and the Northern Line Extension anchor a still-completing riverside regeneration zone with heavy new-build supply and strong international-tenant demand.
Google UK’s headquarters and Central Saint Martins anchor a tech/creative-sector office district built around the UK’s best-connected rail, Underground and Eurostar hub.
Tate Modern, Borough Market and the South Bank cultural corridor drive strong short-let and tourism-adjacent demand alongside a deep professional-tenant pool.
A City-fringe location built around the Goodman’s Fields development, pulling financial and professional tenants priced out of the Square Mile itself.
A £4bn+ regeneration (Elephant Park) with new-build supply at a lower price point than most of Zone 1, two Underground lines, and strong student and young-professional demand.
A prime, low-density village high street with the most stable, wealthy owner-occupier and corporate-let tenant base in central London — a capital-preservation rather than high-yield play.
No city on earth concentrates more top universities or global talent — a self-renewing engine of rental demand.
Imperial (9th in the world), UCL, King’s and LSE headline a student population of 400,000-plus — over 120,000 of them international — feeding finance, tech, law and life sciences.
Eleven Tube lines, the Elizabeth Line, a national rail hub and five airports moving around 169 million passengers a year.
Global connectivityLondon is the world’s second financial centre and Europe’s tech capital — generating around a quarter of all UK output.
Major employers with a significant London presence include:
“The world’s #2 financial centre, the UK’s most liquid market, an 88,000-home shortfall and a currency that discounts entry for overseas buyers. London remains the global safe haven.”
Book a call and we’ll bring you current, fully-vetted London opportunities — with the real, cost-in numbers behind every one.
*Figures are drawn from public sources including ONS, HESA, Savills and JLL. Forecasts are third-party projections, not guarantees; property values and rents can fall as well as rise. Yields and prices vary by property, area and market conditions. This is general information, not financial advice.
London is a capital-growth and safe-haven play rather than a high-yield one — JLL projects around 21.6% price growth over five years, driven by chronic undersupply against an 88,000-home annual need. If you're after strong day-one cash flow, a regional city will outperform; if you want liquidity, currency stability and long-term capital preservation, London remains the deepest and most liquid property market in the UK.
Gross yields typically run 3–6%, well below regional cities like Liverpool or Glasgow. That's the trade-off for London's liquidity and world-city status — investors here are usually optimising for capital growth and resilience, not headline income. Run your own numbers on our yield calculator.
The biggest active regeneration is concentrated around Old Oak Common (the HS2 super-hub, £26bn), Nine Elms/Battersea (unlocked by the Northern Line Extension), Canada Water (British Land's 53-acre new town centre) and Stratford/East Bank (the Olympic-legacy culture and education quarter). Each has a different risk/timeline profile — we'll talk you through which fits your goal.
Some of it is already priced in, but Savills research shows properties near Elizabeth Line stations are still outperforming the wider market by around 7 percentage points — and several stretches of the line are still maturing as an investment case, not fully built out yet. It's not a one-off spike; it's an ongoing effect as the areas around newer stations continue to develop.
No. Most of our overseas clients complete their London purchases entirely remotely — sourcing, due diligence, conveyancing, financing and management can all be handled without a flight. See our guide for overseas investors.
London’s average gross yield (around 5.1%, Zoopla) is lower than the regional cities on this site — that’s the trade-off for a global safe-haven capital with chronic undersupply and the strongest liquidity in the country. It’s a capital-growth and wealth-preservation play first, income second; if yield is your priority, a city like Liverpool or Glasgow will outperform London on that specific metric.
Non-UK residents pay a 2% Stamp Duty Land Tax surcharge on top of all other applicable rates, which stacks with the standard 5-percentage-point surcharge on additional/buy-to-let properties — so a non-resident buying a second property here pays 7 percentage points above the standard residential rate (GOV.UK; Deloitte TaxScape, current 2025/26 rates). We’ll model the exact figure for any specific property before you commit, and our stamp duty calculator gives you a fast estimate.
One email a month: a shortlist of current, fully-underwritten UK opportunities with real net figures — plus a short read on where the market is moving. No spam, no hard sell, unsubscribe in one click.