Data snapshot as of August 2026 — the market moves month to month, so treat the figures below as a point-in-time read, not a live number. For today's numbers on a specific property, use our yield calculator or mortgage checker.
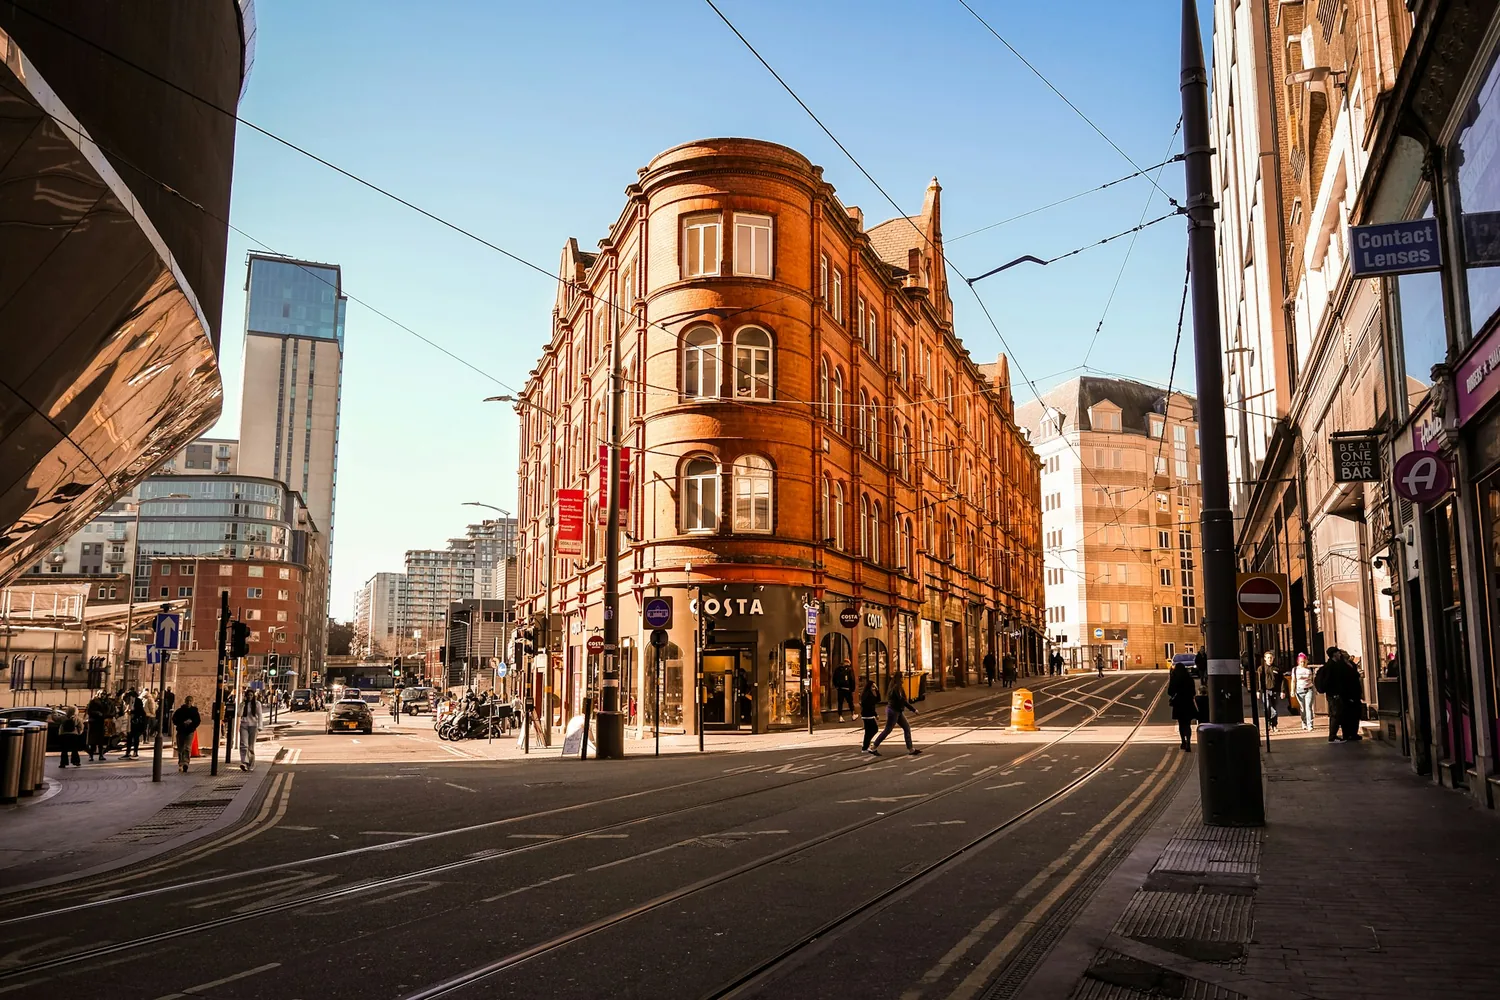
Birmingham city centre — photo by John Evans, via Wikimedia Commons (CC BY-SA 2.0).
Halifax's house price index turned negative in August — down 0.2% on the month, the first annual fall it's recorded since November 2023. Read only the headline and you'd think the market had turned. Look at the regional breakdown behind it and the story is far more specific: the North West of England grew 4.7% in the year to June, the strongest of any English region, while London fell 2.5%. A national average is just that — an average of two very different markets. The one we source in is still the stronger one.
The North–South gap just got wider
The official UK House Price Index — published jointly by HM Land Registry and the ONS — confirms it in its June 2026 release: the North West is the UK's best-performing region on an annual basis, at +4.7%, against a UK average of +2.0% and London at −2.5%. It's the same divide we wrote about in July, and if anything it's become more pronounced as the softer national indices have pulled the headline number down without touching what's actually happening in the North West.
Annual house price growth to June 2026
HM Land Registry / ONS UK House Price Index · hover a bar for detail
Manchester and Liverpool both sit inside the North West figure — the region leading the country is the one this page sources in.
Birmingham's case doesn't rest on a monthly index
Price indices move month to month; infrastructure spend doesn't. HS2's Bromford Tunnel reached its second breakthrough in October 2025, the six-platform Curzon Street terminus — the only HS2 terminus outside London — remains on track, and the Washwood Heath rolling-stock depot contract has now been awarded. The government's own six-monthly report to Parliament (May 2026) puts the West Midlands uplift from HS2 at £20bn and 49,000 jobs, with 63,000 homes planned around the route over the next decade. Whatever a single month's price index does, that's a decade-long structural case that doesn't reverse on one data release.
What it means for investors
This is the same map we already work from, reinforced rather than changed. We source in Manchester, Liverpool and Birmingham because that's where the growth is concentrating — not just on a single good month, but across the price data, the rental market and, in Birmingham's case, a decade of committed infrastructure spend. A softer national headline doesn't change that; it's largely a story about the South.
One caution worth repeating: a headline yield can flatter a deal. The whole job is finding the properties that still stack up on the net figure once voids, management and finance are in — and that's the part we do before a deal ever reaches you.
Sources: HM Land Registry / ONS UK House Price Index, June 2026 (published 2 September 2026); Halifax House Price Index, August 2026; gov.uk, HS2 six-monthly report to Parliament, May 2026; Bank of England Monetary Policy Committee, September 2026. Figures are indicative and move with the market.
Want deals in these markets?
Tell us your budget and strategy and we'll source buy-to-let and HMO opportunities in the North's strongest cities — with the real, net numbers run before you commit.
Make an enquiry